
First home buyers
Still renting? Wondering whether you could afford a home of your own? Let’s find out together.
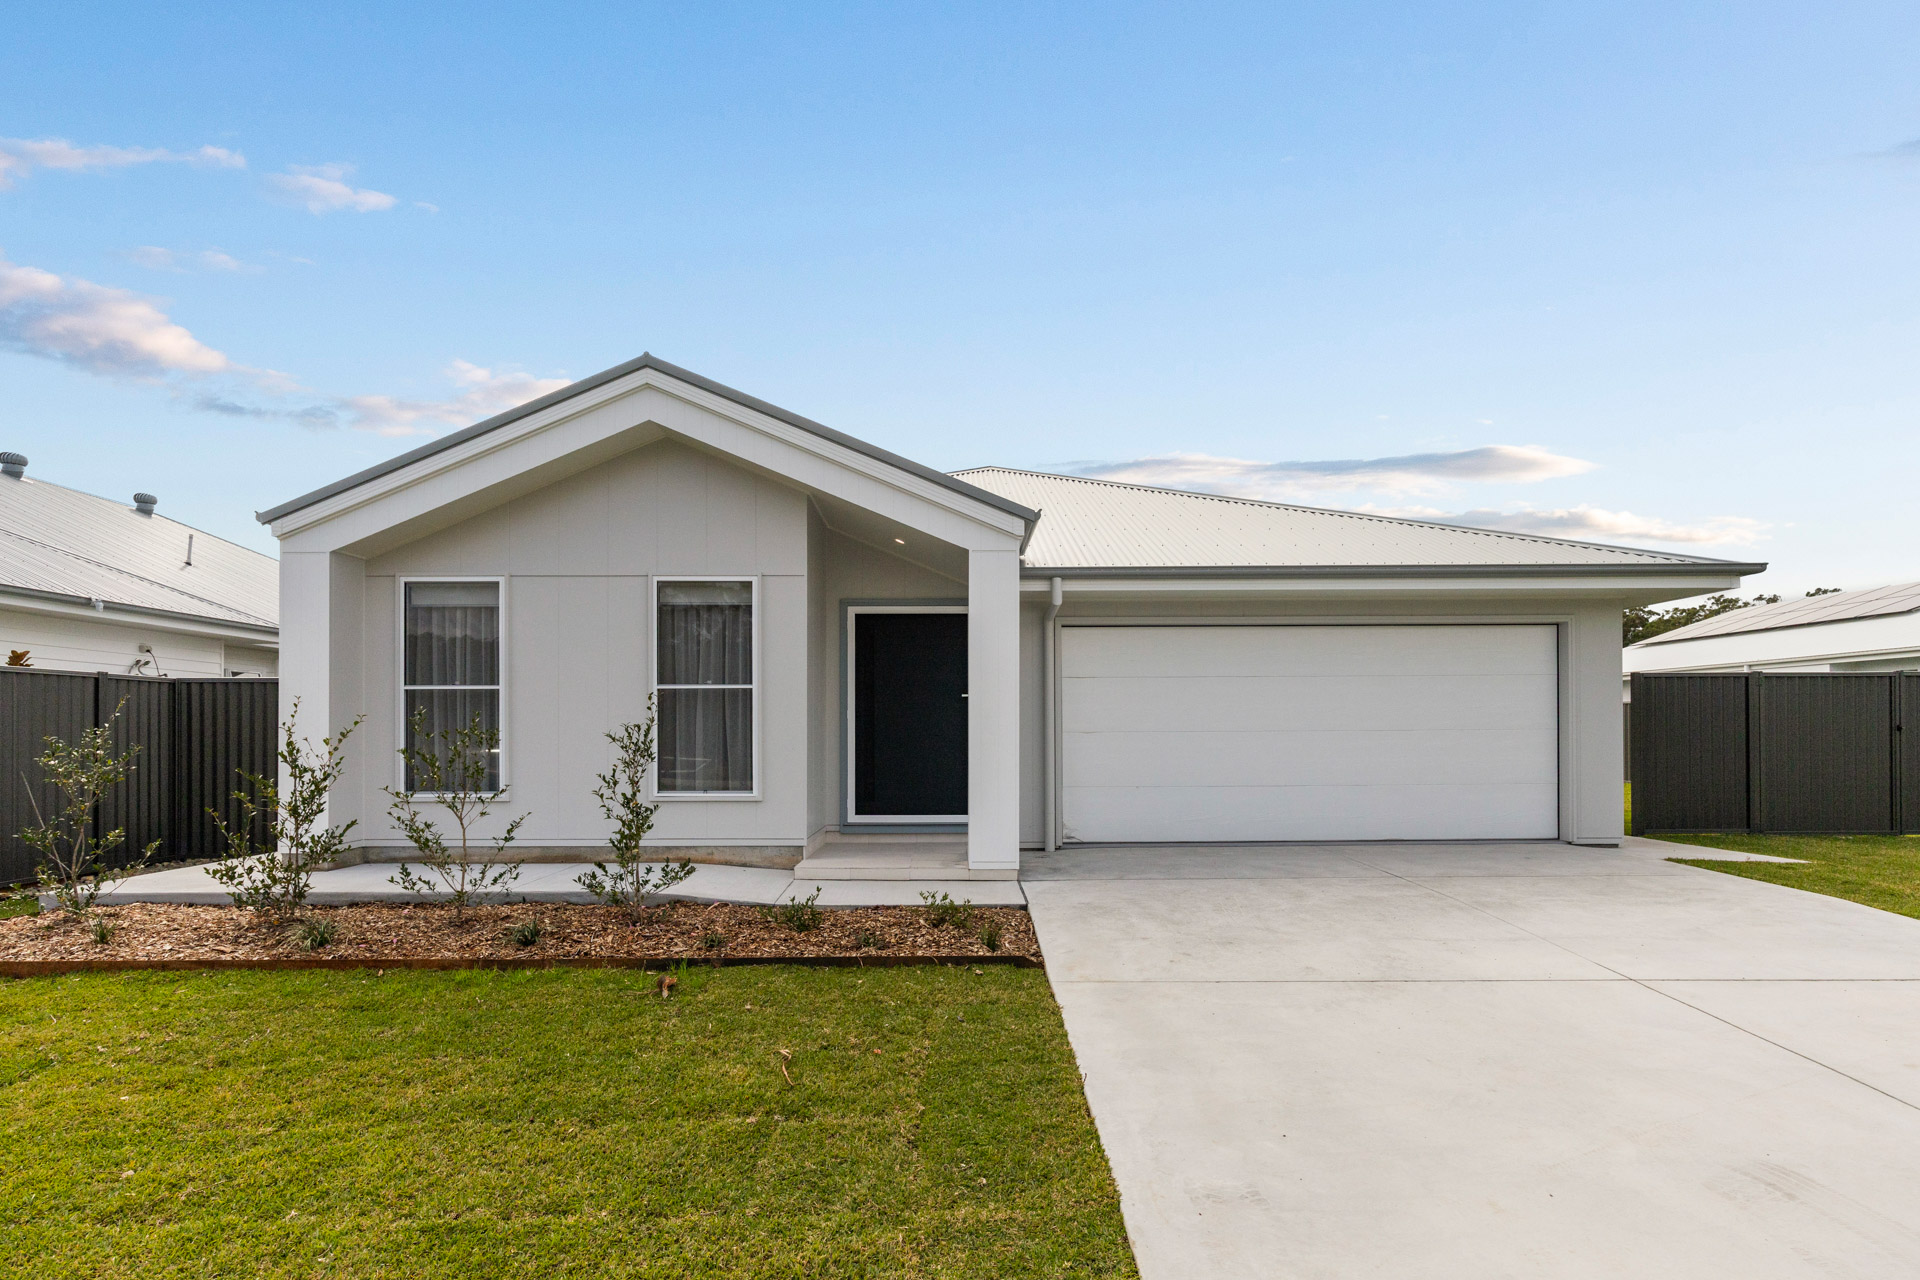
Saving a deposit while paying rent can feel like you’re standing still. And with different grants, government schemes and finance options, it’s hard to know where to start.
At Own A Home Now, we help bring everything together: understanding your budget, finding a brand-new home that suits you, and connecting you with trusted lenders who guide you through the finance process.
You don’t need to have it all worked out before you enquire. That’s where we start.
Understand your options
Depending on your circumstances and the home you choose, government support could help you buy with a smaller deposit, save on stamp duty or reduce the amount you need to borrow.
No stamp duty on eligible NSW homes up to $800,000.
A low-deposit pathway without Lenders Mortgage Insurance for eligible buyers.
A government equity contribution could reduce your mortgage.
Eligibility, price limits and lending criteria apply. Explore each benefit below.
Under the NSW First Home Buyers Assistance Scheme, eligible first home buyers can receive:
| Home value | Stamp duty benefit |
|---|---|
| Up to $800,000 | No transfer duty, commonly called stamp duty |
| Over $800,000 and below $1 million | Reduced stamp duty |
| $1 million or more | No first home buyer concession under this scheme |
Buying vacant land to build your first home? Eligible land purchases up to $350,000 are exempt, with reduced duty above $350,000 and below $450,000.
That could mean a substantial reduction in your upfront buying costs. Eligibility and living-in-the-home requirements apply.
You may not need to save a 20% deposit.
The Australian Government 5% Deposit Scheme allows eligible first home buyers to purchase with a deposit as low as 5%, without paying Lenders Mortgage Insurance.
There are no income caps and places are uncapped. Your lender still checks that you can afford the loan, and property price limits apply.
The government guarantees part of your loan; it does not pay your deposit or repayments.
In NSW, the property cap is $1.5 million in Sydney and specified regional centres, including Coffs Harbour–Grafton and the Mid North Coast, and $800,000 in other areas. Your lender will confirm the cap for your chosen address.
For example: a 5% deposit on a $799,000 home is $39,950. An eligible NSW first home buyer could also pay no stamp duty at that price. Legal fees and other purchase costs still need to be allowed for.
The NSW First Home Owner (New Homes) Grant provides $10,000 for eligible buyers:
The grant is specifically for qualifying new homes. Being brand new doesn’t automatically make every home eligible—the price and purchase structure matter.
If your chosen home is above these limits, you may still qualify for other assistance, such as stamp duty relief or a low-deposit scheme.
The Australian Government Help to Buy Scheme offers another pathway for eligible buyers.
With a deposit of at least 2%, the government can contribute up to 40% towards a new home, reducing the amount you need to borrow. There is no Lenders Mortgage Insurance.
This is a shared equity arrangement, rather than a cash grant. You own the home, but the government shares in its value. Its share must eventually be repaid, with the amount linked to the home’s value at that time.
Current annual taxable income limits are:
Eligibility, ongoing reviews and limited places apply.
NSW property caps are $1.3 million in Sydney and specified regional centres, including Coffs Harbour–Grafton and the Mid North Coast, and $800,000 elsewhere. Your lender checks the address and your individual purchasing limit.
Eligible single parents and single legal guardians may be able to buy with as little as a 2% deposit and no Lenders Mortgage Insurance through the single parent pathway of the Australian Government 5% Deposit Scheme.
Your lender can explain whether this option suits your circumstances.
The First Home Super Saver Scheme lets eligible buyers use qualifying voluntary super contributions towards their first home.
Up to $15,000 of eligible contributions per financial year, to a total of $50,000 per person, can count towards the scheme, plus associated earnings. Release and tax rules apply; it does not give you access to your compulsory employer contributions.
Some benefits can be combined. Help to Buy and the 5% Deposit Scheme are alternative pathways, but eligible buyers may still receive applicable stamp duty relief and the new home grant. We’ll help you connect with the right people to check your options.
A clear path forward
Tell us where you’d like to live, what you need in a home and where you’re at with your savings. There’s no pressure to have all the answers.
We connect you with trusted lenders who assess your income, savings, existing commitments and potential government assistance.
They’ll explain your likely borrowing range, deposit requirements, upfront costs and estimated repayments—so you can understand what buying would mean for your everyday budget.
With that budget in mind, we help you shortlist suitable homes while your lender guides you through finance pre-approval.
The aim is to bring the home and the finance together, with a clear understanding of what you can afford.
Once you’ve selected your home, your lender completes the property assessment and remaining checks needed for unconditional finance approval.
We help coordinate with your lender and conveyancer so you understand the next steps. Pre-approval is conditional; final approval comes from your lender.
When your home is ready and settlement is complete, it’s time to start your next chapter.
Your own front door. Your own space. A place to settle in and make yours.
Full turnkey. Finished for living.
Your first home should be something to look forward to.
All our homes come turnkey and move-in ready on completion, including:
You also have the reassurance of builder warranties, statutory building protections and applicable appliance warranties, subject to their terms.
That means you can focus on settling in, with the main finishing touches already taken care of.
Your first step starts here
If you’re tired of paying rent and wondering when it will be your turn, start with a conversation.
You don’t need finance pre-approval before contacting us. We’ll help you understand the next steps, connect you with trusted lenders and look for a brand-new home within your assessed budget.
Let’s find out what your first home could look like.
Government scheme information checked 23 October 2026. Eligibility, property limits, residency requirements and lending criteria apply. Benefits are not available to every buyer or every home. Your lender and conveyancer will confirm what applies to you. Own A Home Now helps with your property search and introductions; finance advice and approval are provided by your lender or broker.